Introduction
Brands can benchmark UK grocery markets more effectively by combining store-level product prices, competitor assortments, promotions, locations, and historical observations. Store-level data shows where prices differ, which products change, and how competitors respond—turning fragmented retail information into actionable pricing intelligence.
UK Grocery Market Benchmarking Intelligence 2026 is increasingly important for CPG brands, retailers, pricing teams, category managers, and market intelligence professionals operating in a highly competitive grocery environment. National inflation statistics explain broad market movements, but they do not show how an individual product is priced at different retailers or locations.
A structured UK supermarket industry data Scraper 2026 program can capture product names, brands, categories, pack sizes, regular prices, promotional prices, availability, retailer information, store or location details, and collection timestamps. This creates a historical foundation for competitor benchmarking and pricing analysis.
The commercial value becomes clearer when Brands Use Store-Level Price Data to answer practical questions: Which competitor is cheapest for a priority SKU? Where are regional price gaps emerging? Which promotions are temporary? Are private-label products gaining price advantages? Which categories show the greatest volatility?
The Office for National Statistics shows how rapidly the UK food-price environment has changed. Its food and non-alcoholic beverages index increased sharply through 2022 and 2023 before moderating. In June 2026, food and non-alcoholic beverage prices were 1.7% higher year over year, down from 2.2% in May.
For a pricing manager, therefore, the challenge is not simply understanding inflation. It is understanding where price changes occur, when they occur, which products are affected, and how competitors respond.
How Can Brands Compare Prices Across Major UK Grocery Retailers?
Scrape UK Grocery Store Prices to build a structured view of product-level pricing across supermarkets, grocery websites, and relevant retail channels. The objective is to create comparable observations rather than isolated price snapshots.
The UK grocery market includes major retailers such as Tesco, Sainsbury's, Asda, Aldi, Lidl, Morrisons, Waitrose, Co-op, and Iceland. Each retailer may use different promotional mechanics, pack sizes, private-label strategies, and regional pricing approaches.
The phrase Biggest Food Chains in the UK covers retailers that collectively influence a large portion of consumer grocery spending. For brands, benchmarking these retailers can reveal how a product's price position changes across different competitive environments.
A useful dataset should capture:
| Data point |
Benchmarking purpose |
| Product name |
Product identification |
| Brand |
Brand comparison |
| SKU/GTIN |
Product matching |
| Pack size |
Unit-price normalization |
| Regular price |
Base-price benchmarking |
| Promotional price |
Discount analysis |
| Promotion type |
Offer comparison |
| Retailer |
Competitor identification |
| Store/location |
Regional analysis |
| Availability |
Stock visibility |
| Timestamp |
Historical tracking |
2020–2026 market development
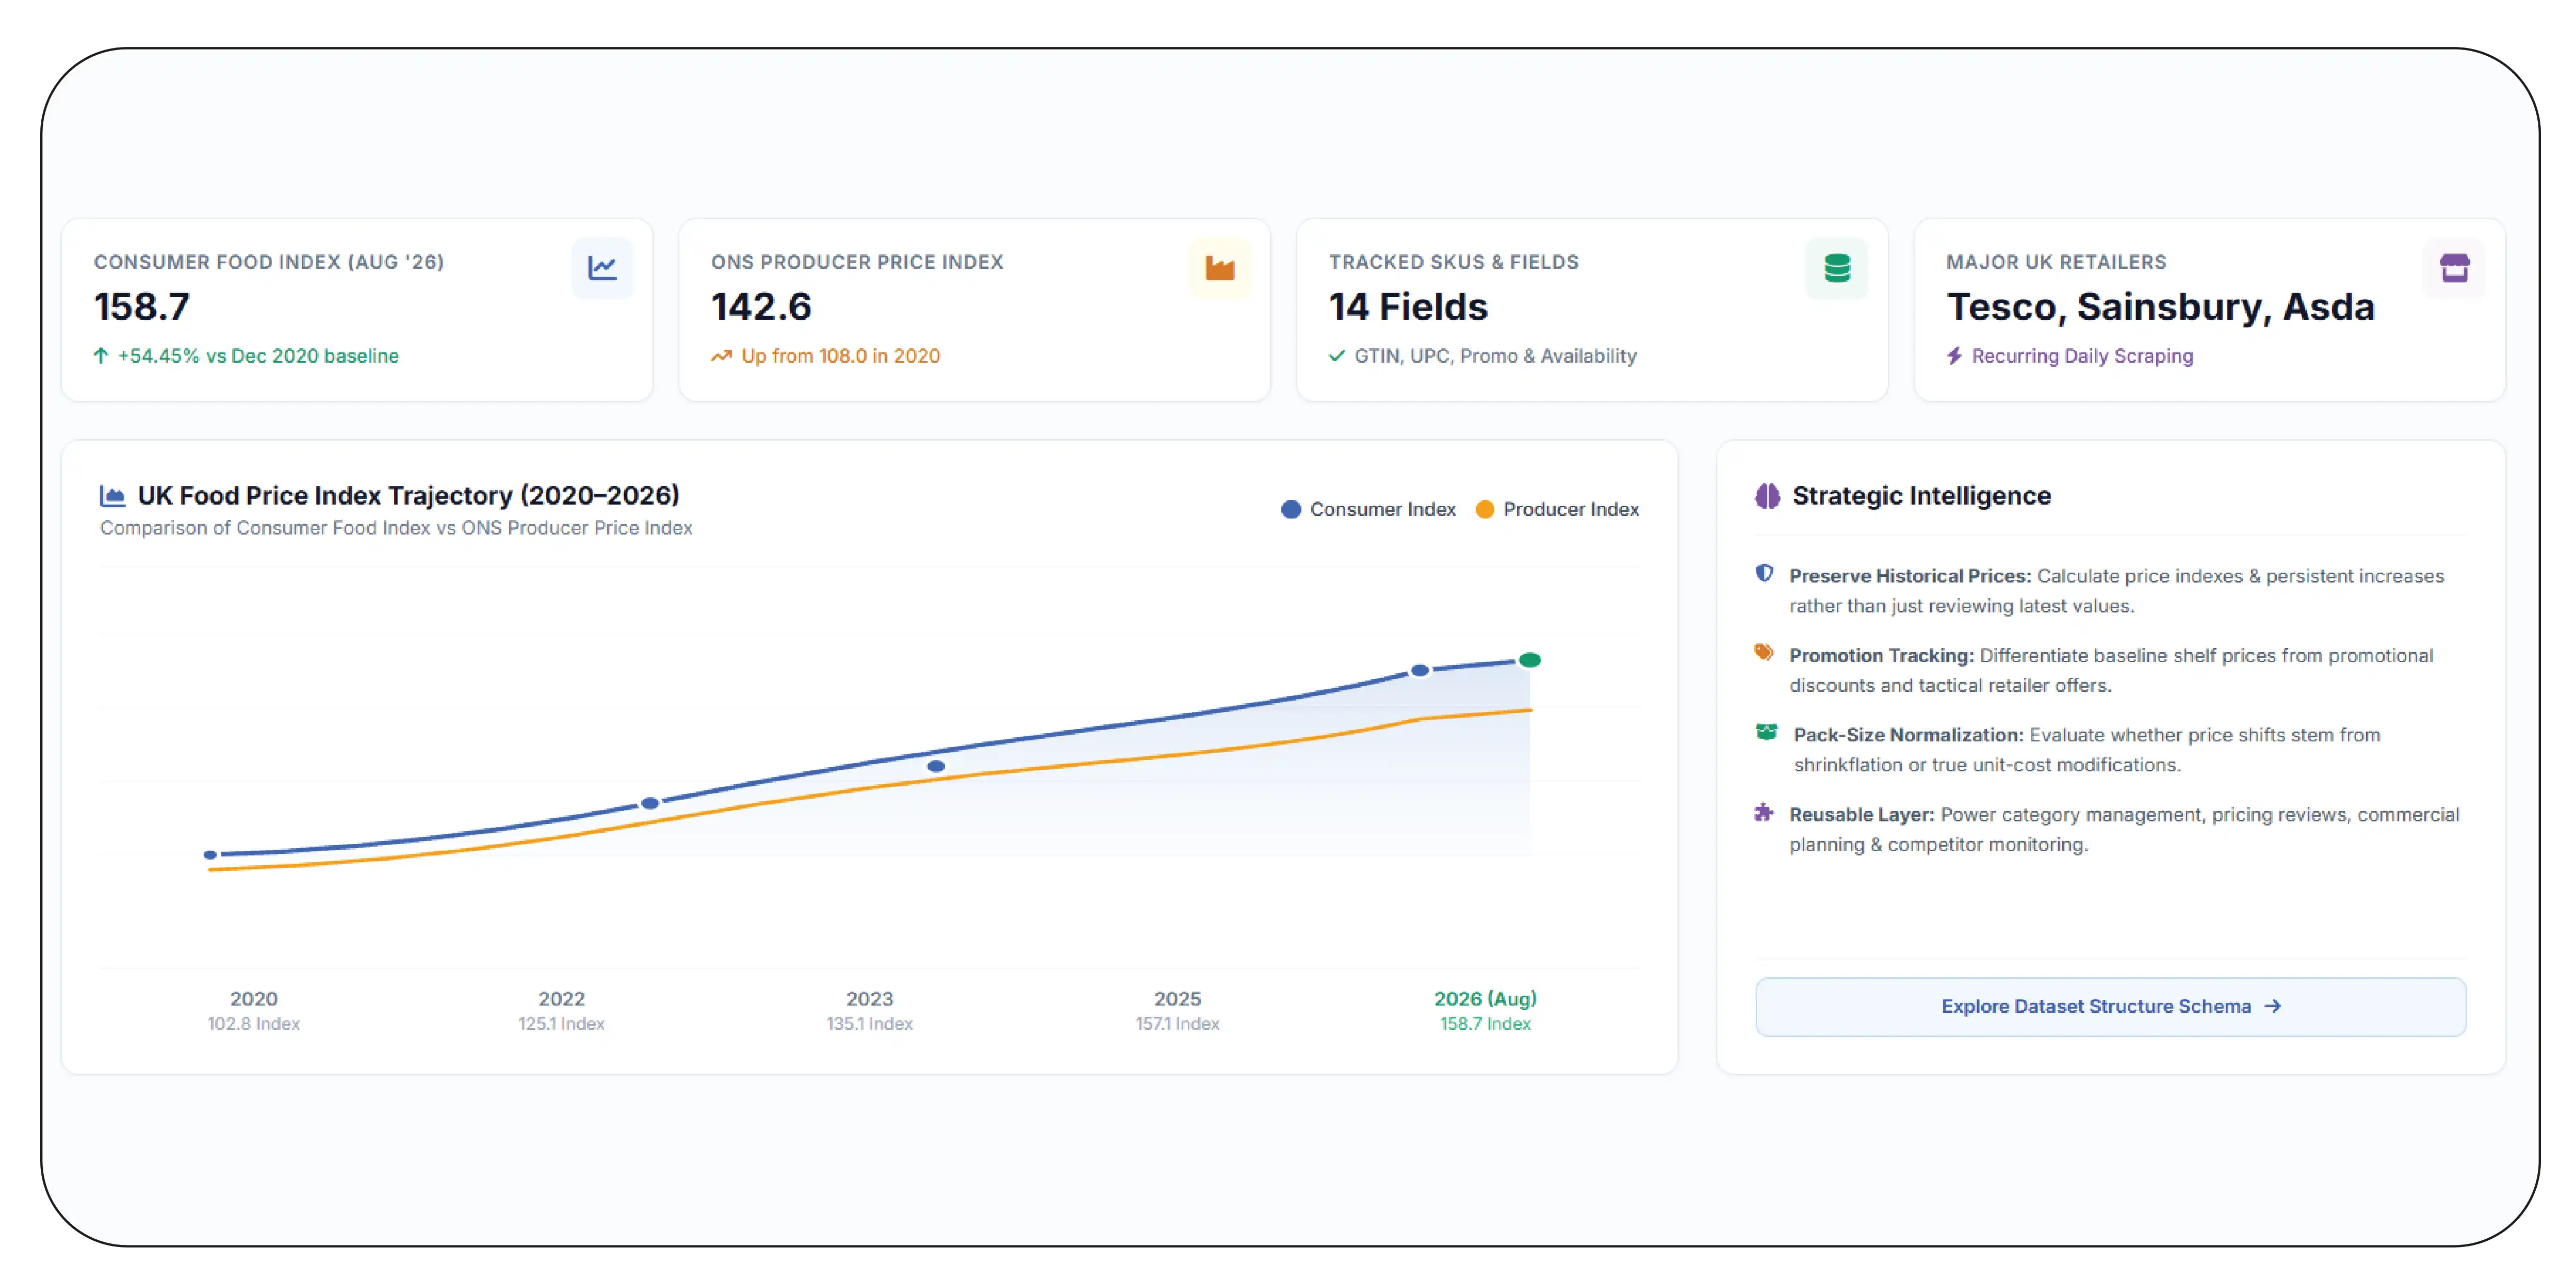
The 2020–2026 period provides an important benchmark for understanding UK grocery pricing. ONS producer-price data for food products shows an index of 108.0 in 2020, rising to 111.0 in 2021 and then accelerating to 124.4 in 2022 and 135.7 in 2023. The index reached 137.3 in 2024 and 142.6 in 2025.
Consumer food prices followed a similarly significant upward path. The ONS food and non-alcoholic beverages index moved from 2020 levels through a pronounced increase in 2022 and 2023. Monthly observations show the index reaching 125.1 in December 2022 and 135.1 by December 2023.
By 2024, the rate of change had moderated considerably, but prices remained at historically higher levels. In 2025, the index increased again, with the food index reaching 157.1 in December. In 2026, monthly food-product observations remained elevated, reaching 158.7 in August on the ONS 2015=100 series.
For brands, these movements demonstrate why historical store-level pricing matters. A national index can identify inflation, but retailer-level datasets explain how individual products contribute to the observed movement. Brands can compare identical SKUs, normalize pack sizes, identify retailer price gaps, and distinguish market-wide increases from competitor-specific decisions.
What Does Store-Level Data Reveal About UK Grocery Competition?
Scrape UK Grocery Store-Level Data to connect individual products with specific retail locations and collection periods. This is especially valuable for businesses selling through multiple grocery channels where pricing and promotions may vary by retailer or region.
Store-level data can help category managers investigate differences between London, Manchester, Birmingham, Glasgow, Cardiff, Leeds, and other UK markets. UK Grocery Product Data Extraction can also help identify whether a competitor's pricing strategy is consistent nationally or varies by location.
A store-level dataset can include:
| Dimension |
Example insight |
| Retailer |
Which supermarket carries the SKU? |
| Store |
Which physical location is observed? |
| Region |
Where is pricing different? |
| Product |
Which SKU changed? |
| Pack size |
Are comparisons like-for-like? |
| Price |
What is the current shelf or online price? |
| Promotion |
Is the product discounted? |
| Date |
When did the change occur? |
| Availability |
Is the product currently listed? |
2020–2026 market development
The UK's inflation cycle changed the importance of detailed retail data. In 2020 and 2021, grocery businesses operated through pandemic-related changes in consumer behaviour and supply conditions. By 2022, food prices were rising rapidly, and ONS producer-price data shows food-product prices moving from an index of 111.0 in 2021 to 124.4 in 2022.
The producer-price index increased again to 135.7 in 2023. It then grew more slowly to 137.3 in 2024 and 142.6 in 2025. This progression demonstrates a key analytical issue: slowing inflation does not mean retailers return to previous price levels. It means the rate of increase changes.
Consumer food prices also show this distinction. The ONS food and non-alcoholic beverages index rose substantially between 2021 and 2023, then moved through a more moderate period in 2024 and 2025.
In 2026, food inflation remained positive but moderated. ONS reported food and non-alcoholic beverage prices were 1.7% higher year over year in June 2026, compared with 2.2% in May.
Store-level monitoring gives brands a way to interpret these macroeconomic movements operationally. Instead of asking only whether grocery inflation is rising, teams can ask whether a particular competitor changed a particular SKU in a particular market. That distinction can directly support pricing, promotion, and assortment decisions.
How Can CPG Brands Detect Competitive Price Gaps?
UK Grocery Competitive Intelligence for Brands combines pricing, assortment, promotion, availability, and historical data to explain competitor behaviour.
A pricing team can use recurring observations to calculate competitor price indexes, price gaps, discount frequency, and price-change frequency. The goal is not simply to find the cheapest retailer. The objective is to understand the competitive position of each product.
Price monitoring becomes more useful when it follows a consistent methodology. Every observation should use standardized product identifiers, comparable pack sizes, clear promotion flags, and reliable timestamps.
For example, a CPG brand could monitor 2,000 priority SKUs across five retailers every week. The resulting dataset could answer:
- Which SKUs changed price this week?
- Which retailer introduced the largest discount?
- Which products are consistently priced above the market median?
- Which competitors have the highest promotional frequency?
- Are price gaps widening or narrowing?
- Are regional differences becoming more significant?
| KPI |
Formula/approach |
Use |
| Price gap |
Brand price − competitor price |
Competitive positioning |
| Price index |
Brand price ÷ market benchmark |
Relative price position |
| Discount depth |
Regular price − promotional price |
Promotion analysis |
| Promo frequency |
Promotional observations ÷ total observations |
Retailer strategy |
| WoW change |
Current price vs prior week |
Short-term monitoring |
| Price volatility |
Frequency/magnitude of changes |
Risk identification |
2020–2026 market development
Between 2020 and 2026, UK grocery pricing moved from relatively stable pre-pandemic conditions through significant inflationary pressure and then into a period of slower price growth. ONS producer-price data records food-product index values of 108.0 in 2020, 111.0 in 2021, 124.4 in 2022, 135.7 in 2023, 137.3 in 2024, and 142.6 in 2025.
This six-year progression illustrates why historical benchmarking matters. If a brand only compares today's price with yesterday's price, it can identify immediate changes but cannot determine whether the current price is unusually high, normal for the season, or part of a long-term trend.
The consumer food index also demonstrates the importance of temporal comparisons. The ONS series shows a major increase during 2022 and 2023, followed by more moderate movements during 2024 and 2025.
In June 2026, food and non-alcoholic beverage prices increased 1.7% year over year, while prices fell 0.2% month over month. This combination shows why weekly and monthly monitoring can provide different signals.
A competitive intelligence program can therefore combine three levels: macroeconomic context, retailer-level benchmarking, and SKU-level observations. The result is a more complete view of whether a price movement reflects the wider market or a specific competitor strategy.
How Can Teams Measure UK Grocery Price Movements More Precisely?
UK Grocery Market Price Analysis should combine current prices with historical observations, unit-price calculations, promotions, and retailer comparisons.
A simple price list can tell a team what a product costs today. A proper market-analysis dataset can tell them how that price changed, how competitors changed, whether the product is on promotion, and how the current price compares with its historical range.
For accurate analysis, businesses should normalize:
- Product identifiers.
- Brand names.
- Product categories.
- Pack sizes.
- Units of measurement.
- Regular and promotional prices.
- Retailer names.
- Store or geographic identifiers.
- Collection dates.
- Availability status.
| Analysis |
What it reveals |
| Weekly price movement |
Immediate competitive changes |
| Monthly average |
Short-term market direction |
| Year-over-year comparison |
Longer-term price movement |
| Retailer median |
Competitive benchmark |
| Unit-price comparison |
True like-for-like pricing |
| Promotion analysis |
Discount strategy |
| Regional comparison |
Store/location differences |
| Price volatility |
Product/category instability |
2020–2026 market development
The ONS food index provides a useful historical reference for the UK grocery market. Food prices increased strongly through 2022 and 2023, with the food-product CPI index moving from 108.6 in December 2021 to 134.7 in December 2022 and 151.8 in December 2023.
During 2024, the monthly index moderated from 150.3 in January to 149.5 in December. In 2025, it moved higher, reaching 157.1 in December. In 2026, monthly observations included 154.3 in January, 156.8 in April, and 158.7 in August.
These movements show why brands should retain historical observations instead of overwriting old prices. A current-price dataset without historical records cannot answer whether a product has experienced repeated increases, temporary discounts, or seasonal fluctuations.
For category managers, this historical layer can support price elasticity research, promotional reviews, assortment planning, and competitor benchmarking. For pricing teams, it can identify products that require immediate review.
The most useful analysis therefore combines breadth and depth: breadth across retailers, stores, categories, and products; depth across weeks, months, and years. This structure allows businesses to move beyond static competitor snapshots and understand the trajectory of the market.
How Can a Structured Benchmark Dataset Support Pricing Decisions?
UK Grocery Price Benchmark Dataset creates a standardized foundation for comparing products, retailers, stores, categories, and historical periods.
Grocery data scraping can collect publicly accessible product information from relevant grocery websites and digital retail channels on a recurring basis. Once collected, the data should be cleaned and normalized before it reaches analytical dashboards.
A benchmark dataset can contain:
| Dataset field |
Recommended purpose |
| Product ID |
Product matching |
| GTIN/UPC/EAN |
Identifier matching |
| Product name |
Search and classification |
| Brand |
Brand benchmarking |
| Category |
Category-level analysis |
| Pack size |
Unit-price normalization |
| Regular price |
Baseline |
| Sale price |
Promotion tracking |
| Discount |
Promotional analysis |
| Retailer |
Competitor identification |
| Store/location |
Local benchmarking |
| Availability |
Supply visibility |
| Timestamp |
Historical analysis |
2020–2026 market development
The UK food-price environment from 2020 through 2026 supports the need for structured historical datasets. ONS producer-price data records food-product index values increasing from 108.0 in 2020 to 124.4 in 2022, 135.7 in 2023, 137.3 in 2024, and 142.6 in 2025.
The consumer food index also moved significantly during the same period. The monthly series shows the index rising from 102.8 in December 2020 to 125.1 in December 2022 and 135.1 in December 2023.
By 2025, the food index reached 157.1 in December. In August 2026, it stood at 158.7, demonstrating that food prices remained substantially above earlier years even though the rate of inflation had moderated compared with the peak period.
For brands, this distinction is critical. A benchmark dataset should preserve historical prices rather than simply reporting the latest value. Historical observations enable teams to calculate price indexes, identify recurring promotions, detect persistent increases, and evaluate competitive positioning.
The dataset can also be connected with product attributes and store-level information. This allows a brand to determine whether pricing changes are associated with pack-size differences, geographic markets, retailer strategies, or promotional activity.
A well-designed benchmark therefore becomes more than a spreadsheet. It becomes a reusable intelligence layer for category management, pricing reviews, commercial planning, and competitor monitoring.
What Should a Store-Level Pricing Dataset Contain?
Store-Level UK Grocery Market Pricing Dataset should connect every pricing observation to a product, retailer, location, date, and commercial context.
For example, a brand may discover that a product sells at different prices across stores in different regions. Without location-level data, that difference may appear inconsistent or unexplained. With store-level observations, the business can determine whether the variation is systematic.
The dataset should ideally include:
- Retailer and store identifier
- Geographic area
- Product and brand
- SKU or GTIN
- Category and subcategory
- Pack size
- Regular price
- Promotional price
- Discount information
- Availability
- Product URL
- Collection timestamp
- Historical price
- Price-change indicator
| Layer |
Example question |
| Product |
Which SKU changed price? |
| Store |
Where did the change occur? |
| Retailer |
Which competitor changed first? |
| Region |
Is the change geographically concentrated? |
| Promotion |
Was the change temporary? |
| Time |
Is the change recurring? |
| Category |
Is the movement market-wide? |
2020–2026 market development
The 2020–2026 period highlights the difference between national statistics and local retail intelligence. National food indexes provide a broad market signal, but they cannot explain every store, SKU, promotion, or retailer decision.
ONS data shows that food-product producer prices rose from an index of 108.0 in 2020 to 142.6 in 2025. Consumer food prices also increased substantially, with the food and non-alcoholic beverages index reaching 135.1 by December 2023 and continuing to move at elevated levels thereafter.
In June 2026, ONS reported food and non-alcoholic beverage inflation of 1.7% year over year, down from 2.2% in May. This illustrates a more moderate inflation environment than the sharp increases seen earlier in the decade.
However, moderation at the national level does not remove the need for store-level monitoring. Individual retailers can still adjust prices differently, promotions can create temporary price gaps, and regional conditions can produce different competitive outcomes.
A store-level dataset gives commercial teams the evidence needed to investigate these differences. It supports localized benchmarking, competitor price alerts, promotion analysis, and historical comparisons. For brands operating across multiple UK channels, this granular view can complement national market statistics and provide a clearer explanation of actual retail conditions.
Why Choose Product Data Scrape?
Product Data Scrape can support brands that need structured grocery intelligence rather than disconnected pricing snapshots. A scalable collection framework can capture product, price, promotion, availability, retailer, store, and timestamp fields according to defined business requirements.
The resulting datasets can be normalized and prepared for competitive benchmarking, category analysis, historical tracking, dashboards, and recurring reporting.
The approach is particularly useful for CPG brands and retailers that need to monitor large SKU universes across multiple UK grocery channels. Historical records can also help identify recurring price movements and distinguish temporary promotions from sustained changes.
With customized fields, scheduled collection, validation, and analytics-ready delivery, businesses can create a repeatable foundation for grocery market intelligence instead of relying on manual checks.
Conclusion
UK grocery competition requires more than national inflation statistics. Brands need product-level and location-level evidence to understand competitor pricing, promotions, assortment changes, and regional differences.
Scrape UK High-Street Store Closing Data can also complement grocery intelligence by providing a wider view of physical retail-network changes and helping businesses contextualize store-level competitive movements.
UK Grocery Market Benchmarking Intelligence 2026 gives brands a framework for combining historical pricing, retailer comparisons, store observations, and category trends. ONS data shows that food prices remain elevated compared with earlier years, making consistent benchmarking valuable for commercial teams.
Work with Product Data Scrape to build a customized UK grocery benchmarking solution covering your priority retailers, stores, SKUs, categories, prices, promotions, and competitive intelligence requirements!
FAQs
1. What is UK grocery market benchmarking?
UK grocery market benchmarking compares product prices, promotions, assortment, availability, and other retail signals across supermarkets, stores, categories, regions, and historical periods.
2. Why is store-level grocery data important?
Store-level data reveals regional price differences, local promotions, assortment variations, and competitor movements that national averages cannot identify with sufficient product-level detail.
3. What information should a grocery benchmark dataset contain?
A useful dataset includes product identifiers, brands, categories, pack sizes, prices, promotions, availability, retailers, stores, locations, timestamps, and historical observations.
4. Can Product Data Scrape collect customized UK grocery data?
Yes. Product Data Scrape can support customized collection requirements covering selected retailers, product categories, SKUs, locations, pricing attributes, promotions, and recurring delivery schedules.
5. How frequently should grocery prices be monitored?
Weekly monitoring works well for competitive benchmarking, while high-priority products and volatile categories may require more frequent collection to capture rapid pricing or promotional changes.


 Singapore
 EMAIL
 PHONE


.webp "thumb")




.webp)